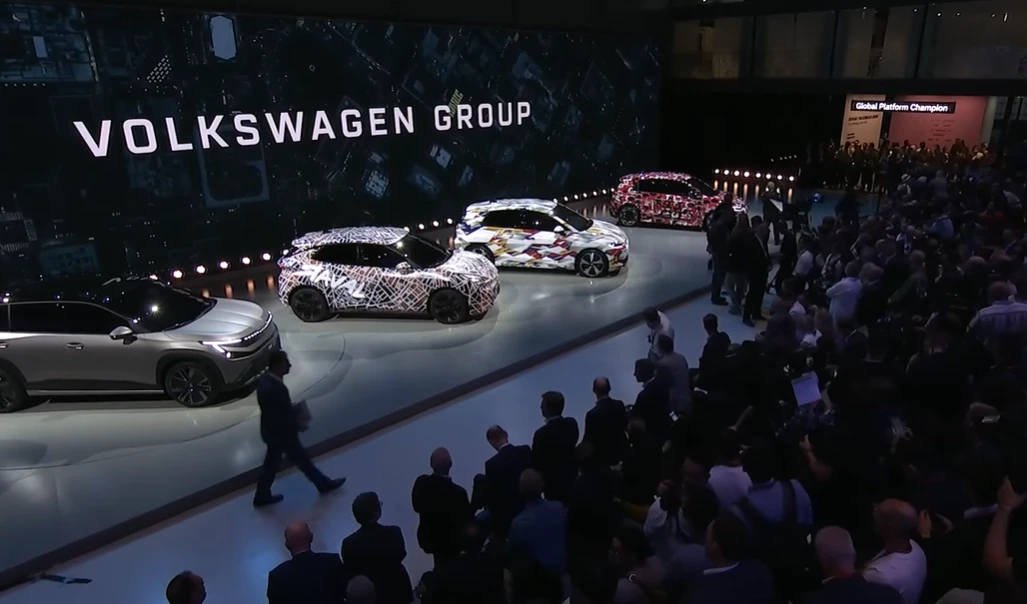
Volkswagen’s supervisory board has approved cutting 100,000 jobs and closing four German plants in the biggest corporate restructuring in automotive history. Here is a complete analytical breakdown of why it happened, who is affected, and what it means for Germany and Europe.
On September 4, 2026, Volkswagen’s supervisory board unanimously approved what the company’s own chief executive called a strong signal for the future. What that signal actually means is the elimination of 100,000 jobs, the largest workforce reduction in the history of the global automotive industry, and the potential closure of four German factories that together represent the heart of a carmaker that has been synonymous with German industrial identity for 89 years.
Volkswagen is about to shed one in seven of its workers. The German car giant said that management and unions had agreed to cut a further 50,000 jobs by the end of the decade, on top of 50,000 already planned, bringing total losses to 100,000. Ford cut 35,000 jobs and closed five plants in 2002. General Motors cut 74,000 jobs and closed 21 plants in 1991. Volkswagen’s 100,000 is now the largest total on record.
The story of how Europe’s largest carmaker arrived at this moment is the story of the European automotive industry’s existential reckoning with Chinese competition, the unintended consequences of EV transition policy, and the political fragility of a Germany that has built its economic identity around making cars that the world increasingly no longer wants to buy in the way it once did.
How Volkswagen Got Here: A Crisis Years in the Making
The crisis that produced the Future Plan 2030 did not arrive suddenly. It accumulated over several years through a combination of forces that Volkswagen’s management either misread or responded to too slowly.
Europe’s biggest carmaker is under pressure from US tariffs, weaker profit margins on electric vehicles and, above all, fierce competition in China, the world’s largest car market.
China was, for many years, the engine of Volkswagen’s profit. The group sold more cars in China than anywhere else in the world, and the margins earned there subsidised its European operations and funded its transition investments. That equation has inverted with brutal speed. Chinese consumers, once loyal to German premium brands, have pivoted toward domestic EV manufacturers whose technology, software integration, and price points have outcompeted the German incumbents in their own backyard.
In the first quarter of 2026, the group’s net profit slumped by 28% to €1.56bn, while revenue fell by 2% to €75.7bn. The Executive Board has repeatedly stated that the current business model no longer works across all brands: developing cars in Germany, producing them in Europe and exporting them to the world.
That sentence is the plainest possible admission that Volkswagen’s entire operating model, developed over decades of dominance, is no longer viable in the world that exists today. According to data from Mobility Global, Volkswagen’s plants in Germany are operating at 81 percent of their capacity and are set to fall to 73 percent by the end of the decade. In 2026, Zwickau is the best-performing plant among the four at risk of closure, with a capacity utilisation rate of 88 percent, although this is expected to fall to 42 percent by 2030. A factory running at 42 percent capacity is economically indefensible.
The Future Plan 2030: What Was Actually Approved
The automaker’s supervisory board unanimously approved its sweeping Future Plan 2030 on Thursday. It calls for fewer workers, models, options, managers, and investments as Volkswagen tries to cut costs and catch up with faster-moving Chinese rivals.
The plan has several distinct components that together amount to a fundamental reimagining of what Volkswagen is.
Job cuts. The Future Plan 2030 will see around 50,000 jobs cut, on top of 50,000 already previously announced, while several factories around Germany are being kept under review over the next decade. The company had already announced the reduction of 35,000 jobs in Germany by 2030. The 100,000 figure combines previously agreed reductions with the newly approved tranche, but the total is nonetheless historic.
Four plants with no guaranteed future. The four German plants facing an uncertain future are Emden, Zwickau, Hanover, and Audi’s Neckarsulm factory. Volkswagen said it cannot currently secure competitive future production for the sites once their existing vehicle allocations end at staggered points between 2031 and 2034. This is not an official closure announcement yet. Volkswagen says it will look at other uses for the plants, but vehicle production at all four could end.
For the four plants, that leaves an opportunity, but not a guarantee. Their future now depends on whether Volkswagen can assign economically viable products or other industrial activities to them over the coming months.
Model line reduction. The plan calls for slashing the group’s vehicle model lineup by approximately half, simplifying platforms, software architectures, and electronic systems. Complexity has been one of Volkswagen’s most persistent cost problems, with each additional model requiring dedicated development, tooling, and supply chain management costs that have ballooned as the product portfolio expanded.
Management restructuring. The job cuts explicitly include management positions, a detail that signals this is not simply a shop floor workforce reduction but a genuine delayering of the organisational structure. Management is reviewing the future of four German plants and, according to media reports, is considering discontinuing the SEAT brand.
The Union Deal: How Workers Won Some Battles and Lost the War
One of the most remarkable aspects of the Future Plan 2030 is how it was reached. Volkswagen’s workforce in Germany operates under a unique governance structure, with IG Metall, Germany’s most powerful trade union, holding 50 percent of supervisory board seats alongside shareholder representatives. The state of Lower Saxony holds 20 percent of voting rights. Worker representatives have genuine veto power over major decisions in a way that exists nowhere else in the automotive world.
That structure produced months of deeply contested negotiation. IG Metall organised protests by VW workers outside plants across the country throughout the process. Daniela Cavallo, Volkswagen’s chief employee representative, had previously pushed back hard against factory closures. She ultimately backed the plan but made clear that workers should not be left to carry the cost of Volkswagen’s turnaround. “The Future Plan is a necessity to lead our Group successfully into the next decade — without placing the burden of that transformation solely on employees,” Cavallo said.
The union secured several key concessions. The cuts will proceed without compulsory redundancies, relying instead on voluntary departures, early retirements, and attrition. More than 28,000 departures at Volkswagen had already been contractually agreed by June 2026 for completion by 2030. The plants facing closure have not been formally condemned; they have been given time to find new purposes or new products.
But the strategic direction was not negotiable. The scale of the crisis facing Volkswagen is such that even Germany’s most powerful union, in its strongest corporate governance position, could not prevent a restructuring of this magnitude. That is itself a signal about how serious the underlying competitive challenge has become.
The Chinese Competition Factor: The Force Behind Everything
Chinese plug-in hybrids escaped the EU’s 2024 duties on electric vehicles, and their exports to Europe rose from about 3,800 a month in October 2024 to 50,000 in July 2026. That statistic captures, in a single number, the speed and scale of the competitive displacement now occurring in the European automotive market.
Volkswagen is not simply losing market share to Chinese rivals in China. It is now watching Chinese manufacturers take European market share at home. The EU’s tariff measures, designed to protect European carmakers from Chinese competition, have been partially circumvented by the shift to plug-in hybrids, which escaped the duty structure, and by Chinese manufacturers investing in European production capacity, as BYD’s Hungarian factory demonstrates.
The structural problem Volkswagen faces is not simply price. Chinese EV manufacturers, led by BYD and SAIC, have achieved battery technology, software integration, and manufacturing cost curves that European incumbents have not matched. Volkswagen’s EV investments in Zwickau, the plant converted at enormous cost to produce six EV models, produced a factory that is now underutilised because the vehicles it makes are not competitive enough to generate sufficient demand. The Zwickau plant, recently converted to an electric car production site for six EV models across the VW, Audi and Cupra brands, has seen multiple production pauses due to what the company has called weak demand for EVs.
That detail is particularly painful. Volkswagen invested billions in the EV transition at Zwickau, converting it from internal combustion engine production at significant cost and disruption, only to find that the EVs it produces there face demand so weak that the plant cannot run at viable capacity. The EU’s EV mandate created the transition pressure. The Chinese competition that arrived simultaneously ensured that European EVs would not automatically capture the market they were being transitioned toward.
What This Means for Germany: Economic and Political Consequences
Restructuring plans could put over 47,796 jobs at risk in Germany and up to 100,000 globally. For a country where the automotive sector directly employs around 800,000 people and indirectly supports millions more through the supply chain, the impact on specific regions and communities will be severe.
The four plants facing potential closure are concentrated in specific German regions that cannot easily absorb the economic shock. Zwickau, in Saxony, was a city that staked its post-reunification economic revival partly on the Volkswagen factory conversion. Emden, in Lower Saxony, is an industrial port city where the VW plant is one of the largest employers. Hanover and Neckarsulm have similar profiles of dependency.
The political consequences are already visible. The far-right Alternative für Deutschland is soaring, capitalising on fears and frustration, even amongst workers. The AfD won two eastern German state elections in September, delivering a major political setback to Chancellor Friedrich Merz.
The connection between economic anxiety in Germany’s industrial heartland and the AfD’s electoral success is not coincidental. Communities that fear the loss of stable, well-paid manufacturing employment are precisely the communities where populist movements offering simple explanations and assertive national identity politics find their most receptive audiences. Volkswagen’s restructuring is not simply a corporate story. It is a political story about the social contract that Germany’s industrial model underwrote for decades and what happens when that contract is renegotiated under duress.
The SEAT Question and the Broader Group Strategy
Management is reviewing the future of four German plants and, according to media reports, is considering discontinuing the SEAT brand. The potential discontinuation of SEAT, Volkswagen’s Spanish volume brand, would be one of the most significant brand decisions in the group’s history.
SEAT has historically served as the group’s entry-level European brand, competing in the budget segment where Chinese competitors are now most aggressively taking share. If the economics of running a separate brand infrastructure for a price segment that cannot be defended against Chinese competition no longer work, discontinuation becomes a rational corporate response even if it carries enormous human and political costs in Spain.
The broader group model reduction, cutting the total lineup by approximately half, reflects the same logic applied across every brand and every market. Volkswagen’s explosion of models, variants, and configurations over the past two decades created marketing complexity and customer choice but also the manufacturing complexity that is now strangling its cost structure. Fewer, better, more competitive models is the strategy. Whether it is the right strategy in time is the question the next four years will answer.
Who Wins and Who Loses
Chinese EV manufacturers are the clear strategic winners from Volkswagen’s restructuring. Every VW model that is discontinued, every plant that closes, and every engineering team that is disbanded represents reduced competition for BYD, SAIC, Geely, and their peers in both European and global markets. The restructuring validates the competitive advantage they have built and reduces the resources Volkswagen has available to close the gap.
European component suppliers face significant exposure. The automotive supply chain that feeds Volkswagen’s German plants employs hundreds of thousands of additional workers across Germany, Austria, the Czech Republic, and other European countries. Model reductions and plant closures ripple through the supply base with multiplied effect, as each vehicle programme cut reduces orders for seats, electronics, drivetrains, and body components across dozens of supplier companies.
German taxpayers and the federal government face difficult choices. The social costs of 100,000 job cuts, including unemployment benefits, retraining programmes, and regional economic support for affected communities, will fall significantly on public finances. The political pressure to provide state support for affected workers and regions will be intense, particularly given the AfD’s electoral success in the most exposed communities.
Volkswagen shareholders received the Future Plan 2030 as a necessary but painful reset. The supervisory board’s unanimous approval signals that both labour and shareholder representatives judged the plan as the least bad available option. Whether it is sufficient to restore competitiveness is a different question from whether it was necessary. It was necessary. Whether it is sufficient remains to be seen.
European consumers face a market in transition. Fewer Volkswagen models at higher prices, as the group retreats from unprofitable segments, combined with increased Chinese competition in the volume segments Volkswagen is vacating, will reshape the European car market in ways that are difficult to predict with confidence but certain to be significant.
The Three Scenarios for What Comes Next
The recovery scenario sees the Future Plan 2030 succeed on its own terms. Job reductions proceed through voluntary departures and early retirements without industrial action. The four plants under review find new products or new industrial purposes. The simplified model lineup becomes more competitive. Volkswagen’s cost per vehicle falls toward Chinese benchmarks and the group returns to double-digit profit margins by 2030. This scenario requires everything to go right simultaneously, including a stabilisation of Chinese competition, a recovery in European EV demand, and a management team that can execute an unprecedented transformation without losing the engineering talent that constitutes the company’s core competitive asset.
The managed decline scenario sees the restructuring proceed but fail to restore competitiveness. Job cuts happen, plants close, models are discontinued — but the underlying competitive disadvantage relative to Chinese manufacturers is not overcome. Volkswagen stabilises at a smaller scale, focused on premium segments where German engineering retains genuine differentiation, and effectively concedes the volume market to Chinese competitors. This is the scenario that most industry analysts quietly consider the most probable, though few say so publicly.
The political intervention scenario sees the scale of the human cost provoke a political response that changes the terms of the restructuring. Federal and state governments provide significant support in exchange for commitments that slow or limit the job cuts. New EU trade measures provide more effective protection from Chinese competition than the current price undertaking framework. The AfD’s electoral success in affected regions creates irresistible political pressure on the federal government to act. This scenario delays the restructuring but does not resolve the underlying competitive challenge.
What This Means for the European Automotive Industry
Volkswagen’s Future Plan 2030 is not simply a Volkswagen story. It is the most visible manifestation of a structural crisis affecting the European automotive industry as a whole.
Airlines worldwide are cutting back on lower-cost flights due to high fuel prices, which have doubled since the start of the war in Iran. That context matters for the automotive industry because it is reshaping the total cost of mobility in Europe, making the economics of car ownership more challenging for households already under pressure from energy costs, and potentially accelerating the shift toward shared mobility solutions that reduce overall vehicle sales volumes.
Stellantis, Renault, and to a lesser extent BMW and Mercedes-Benz face versions of the same challenges. Chinese competition in volume segments, EV transition costs, and the China revenue decline that has hit Volkswagen most severely affect the entire European industry. Volkswagen’s restructuring is the first domino. It will not be the last.
The European Commission’s response to this crisis will define the industrial policy landscape for the rest of the decade. The EU-China EV trade discussions, ongoing with an October 15-16 European Council review deadline, the REsourceEU critical minerals strategy, and the broader ReArm Europe defence spending expansion that is redirecting industrial capacity toward military production all create a context in which automotive restructuring is happening simultaneously with other major industrial transitions.
Whether Europe emerges from this decade with a viable automotive industry that can compete globally, or whether it becomes a premium niche supplier to a market increasingly dominated by Asian volume manufacturers, depends on decisions being made right now in Wolfsburg, Brussels, Beijing, and Berlin. Volkswagen’s Future Plan 2030 is the most consequential of those decisions to date.
Sources: Euronews Business, June 26, 2026; Euronews, September 4, 2026; Electrek, September 3, 2026; Il Sole 24 ORE; Automotive Manufacturing Solutions; Erste Bank Research, October 2026; Modern Diplomacy, October 9, 2026; Manager Magazin; CNBC; GB News.
Related Articles:
- The EU-China EV Trade War 2026 Explained: Tariffs, Price Floors, Rare Earths and What It Means for Europeans
- Europe’s Fuel Crisis Explained: Why Diesel Has Hit €2.24 a Litre and What Happens Next
- Europe’s Economy Is Defying the Odds: War, Energy Shock and the PMI Paradox of September 2026
- Volkswagen Approves 50,000 Additional Job Cuts, Halves Model Range, and Faces Phase-Out at Four German Plants