France’s 10-year bond yield hit 4.92%, its highest since 2002. Debt stands at 119% of GDP. Streets are burning. Parliament is gridlocked. And a Moody’s decision this week could make it all worse. Here is the complete analytical breakdown.
There is a number that is concentrating minds across European finance ministries, trading floors and the corridors of the European Commission this week, and that number is 4.92. That is the yield France must pay to borrow money for ten years, expressed as a percentage. It is the highest France has paid since 2002, nearly a quarter century ago. It is higher than Italy pays. It is 1.53 percentage points above what Germany pays for the same borrowing, a gap that reflects a market judgement about relative risk that would have seemed unthinkable even three years ago.
Behind that number is a story that has been building for a decade and is now arriving at a reckoning. France has the highest budget deficit of the four largest eurozone economies, at 5.1 percent of GDP in 2025. It carries a public debt of 119 percent of GDP, the highest since the immediate aftermath of the Second World War and the third highest in the European Union, surpassed only by Greece and Italy. Its parliament has been functionally ungovernable since Macron’s disastrous snap elections in 2024. Its streets have been on fire since September. And on October 23, the Moody’s credit rating agency will make a decision on France’s sovereign rating that markets are watching with unusual intensity.
France, truly, is on the brink. That is not a tabloid headline. It is the assessment of the managing director for Europe at Eurasia Group, one of the world’s most respected geopolitical risk consultancies.
How France Got Here: A Decade of Deferred Decisions
The debt trajectory that is now alarming bond markets did not arrive suddenly. It is the cumulative result of a decade of choices, non-choices, and political failures that span multiple governments and the entire Macron presidency.
France has run one of Europe’s highest deficit-to-GDP ratios for nearly a decade under President Emmanuel Macron. Even as thousands take to the streets to protest years of underfunding in public services, particularly education, France has consistently borrowed more than it spent, year after year, without the structural reform programme that might have justified the borrowing as investment rather than consumption.
The numbers from Eurostat, published on October 21, tell a stark story. France ran a 5.1 percent budget deficit in 2025, far above the eurozone average of 2.9 percent. Its interest bill nearly doubled in four years to €65.7 billion, roughly 2.2 percent of GDP, as interest rates rose while the debt pile grew. Government spending is equivalent to about 57 percent of GDP, second only to Finland among OECD countries. A country spending 57 percent of its national output through government has built an enormous social contract. The problem is finding the revenue, and the political will, to honour it sustainably.
Ironically, President Macron has long discussed the reforms needed to improve the fiscal outlook and avoid attracting the ire of bond investors. From 2017 onwards, Macron has spoken of the need for pension reforms to ease the fiscal burden, but this is a lightning-rod political issue in France and attempts at reforms have stalled on multiple occasions. The 2023 pension reform, when it finally passed, required the government to use a constitutional mechanism to bypass a parliamentary vote, an act that generated enormous popular anger and contributed directly to the political fragmentation that now makes governing France so difficult.
The pandemic as well as the Ukraine and Iran wars worsened France’s fiscal picture. The energy shock of 2022 required emergency household support. The energy shock of 2026, driven by the Iran war, has required it again. But while external shocks are by definition unavoidable, France entered each of them carrying more debt than the rules permitted and with less fiscal buffer than its size in the eurozone warranted.
The Riots as a Financial Signal
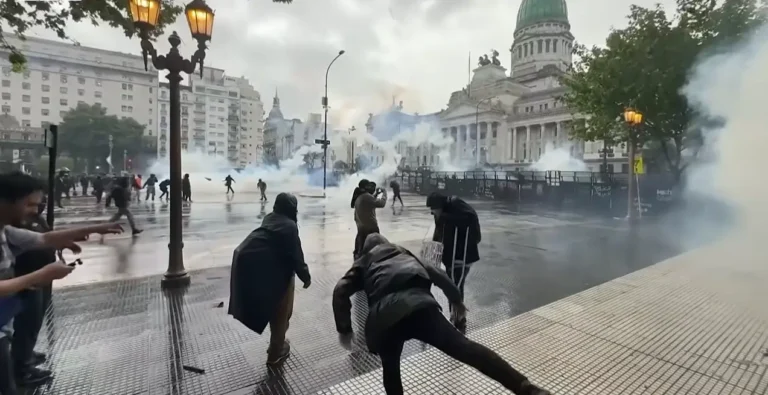
The protests that began on September 18 and escalated dramatically on October 17 are not simply a social story. They are a financial one. The connection between street violence and bond yields is direct and visible in the market data.
French markets tumbled on Monday, October 19, with bonds, Paris-listed stocks and even the euro falling after widespread protests across France underscored difficulties the government faces in reducing its large deficit.
A slide in bond prices on Monday pushed France’s 10-year yield up 13 basis points to 4.9 percent, on track for its largest one-day rise in weeks, while the German 10-year yield, the eurozone benchmark, rose only 4 basis points to 3.45 percent. The difference between those two yields, which reflects the premium investors demand to lend to France rather than Germany, was 146 basis points, and it has been as high as 160 basis points in early October.
At that point, France’s 10-year yield hit 4.99 percent, its highest since 2002. Yields are now heading back towards that level.
Why does street violence move bond markets? The mechanism is straightforward. Investors assessing France’s creditworthiness are not simply looking at its current debt level in isolation. They are asking whether France’s government has the political capacity to implement the spending restraint and revenue measures that would stabilise that debt level over time. Every day of riots, every arrest, every looted storefront, and every school blocked by protesting students is evidence that the political space for austerity measures is shrinking rather than growing. A government that cannot pass a budget without mass social unrest is a government whose fiscal trajectory is becoming harder to control.
France now borrows at a higher rate than Italy. That sentence requires a moment of reflection. Italy is a country that nearly triggered a full eurozone sovereign debt crisis in 2011 and 2012, that has carried a debt-to-GDP ratio above 130 percent for years, and that is routinely described as the most significant systemic risk in the European financial architecture. The fact that bond markets are currently pricing France as a riskier borrower than Italy is a signal of extraordinary severity.
The Budget Battle: Numbers That Do Not Add Up
France’s National Assembly began debate on the revenue side of its 2027 budget on October 20, today, in a political environment that makes reaching agreement on anything a genuine challenge.
The government’s proposal would modestly reduce the deficit to 5 percent of GDP from 5.4 percent, a reduction so small that it has been described as barely a rounding error in the context of France’s structural fiscal challenge. Even this modest consolidation is contested. Moody’s warned that recent unrest could constrain fiscal consolidation efforts and that even the proposed budget will likely do less than hoped, reducing the deficit only to 5.2 percent of GDP rather than the targeted 5 percent, due to weaker GDP growth than the government projected and the political difficulty of implementing real spending cuts.
The government argues that France cannot continue increasing spending without addressing its debt. This is arithmetically true. The problem is that every category of public spending that might plausibly be reduced has a constituency that will fight its reduction in the streets, in parliament, or both.
The education funding demand at the heart of the student protests, €11 billion in additional annual spending, is not a demand that can be reconciled with a budget consolidation that requires spending cuts. The Yellow Vest anger over fuel prices and purchasing power cannot be addressed by measures that reduce the household support programmes that partially cushion those costs. The trade union demands for higher wages and pensions point in the opposite direction from the trajectory that bond markets require.
The danger is a self-reinforcing cycle. Political instability makes investors demand higher yields. Higher yields increase debt-service costs, which already stand at €65.7 billion annually. Higher interest payments force deeper spending cuts. Deeper spending cuts fuel further social unrest. Unrest makes further political instability more likely. And the cycle begins again.
The Moody’s Moment: What Thursday’s Decision Could Mean
Investors are nervously awaiting an October 23 decision by Moody’s on France’s sovereign credit rating, as a downgrade would automatically raise the government’s borrowing costs further.
Moody’s currently rates France at Aa3, two grades below the United States and three below Germany. Its peers Fitch and S&P Global both rate France one notch lower. A downgrade by Moody’s to align with Fitch and S&P would not be catastrophic in isolation, but it would carry immediate practical consequences.
Many institutional investors, including pension funds, insurance companies, and central banks, hold French government bonds in quantities determined partly by rating thresholds. A downgrade triggers automatic portfolio reviews and, in some cases, automatic selling of bonds that no longer meet the minimum rating requirements of the fund’s investment mandate. That selling pressure pushes yields higher, increasing France’s borrowing costs further, in a feedback loop that is self-reinforcing.
A downgrade would also be a significant political signal in the run-up to the 2027 presidential election, providing ammunition to candidates across the spectrum to attack the incumbent government’s economic management. In a presidential race where Le Pen is far ahead in polls and where Mélenchon’s hard-left France Insoumise is competitive in the first round, a Moody’s downgrade hands both candidates a concrete symbol of establishment failure.
Moody’s expects the budget will eventually be adopted, but possibly by decree as the National Assembly dithers. The possibility of a budget passed by executive decree rather than parliamentary vote, repeating the mechanism used for the pension reform, would be another demonstration that France’s democratic institutions are struggling to function under the pressure of the current crisis.
The Political Arithmetic of Paralysis
The roots of France’s current political dysfunction lie in a single decision: Macron’s call for snap legislative elections in June 2024, following the European Parliament elections in which his coalition suffered a heavy defeat at the hands of Le Pen’s National Rally. The snap elections produced a hung parliament in which no bloc has a majority, the political centre has evaporated, and successive prime ministers have found it almost impossible to pass legislation.
Analysts say this political fragmentation, which led to the paralysis of parliament after snap elections called by Macron in 2024 backfired, is likely to persist and is at the core of France’s deepening crisis. The political centre in France has evaporated, allowing the National Rally and Mélenchon’s far-left France Unbowed party to harvest growing public exasperation, while Macron’s successive prime ministers have been unable to pass a budget through Parliament.
Since December 2024, three prime ministers have been toppled or resigned, and Macron has installed his fifth prime minister in two years. Each transition has consumed political capital and legislative time without producing the sustained governance that France’s fiscal situation demands. Sébastien Lecornu, the current prime minister, has already indicated he may seek to declare a state of emergency in response to the October protests, a measure that would carry its own political costs and signal its own kind of institutional failure.
France ran the largest budget deficit of the four big euro-zone economies in 2025, at 5.1 percent of gross domestic product, according to figures from Eurostat published on October 21. Its interest bill nearly doubled in four years to €65.7 billion, about 2.2 percent of GDP.
On October 20, three days after the riots, France paid about 4.92 percent to borrow for ten years, 1.53 percentage points more than Germany. The 146 basis point spread between French and German bond yields, while narrower than the peak seen during the 2011 eurozone sovereign debt crisis, is approaching levels that historically trigger intervention by European institutions and force governments into emergency action.
Le Pen, Mélenchon and the 2027 Election Wildcard
The presidential election is scheduled for spring 2027, and it is casting a long shadow over every fiscal and political decision being made today. Marine Le Pen is far ahead in opinion polls, described by analysts as perceived, rightly or wrongly, as the lesser evil by bond markets compared to the hard-left alternative.
Le Pen has recently sought to bolster her economic credentials by promising €140 billion in savings by 2032 and committing to bring the budget deficit down to 3 percent by 2030. These promises have been received with scepticism by many economists, but they represent a significant shift in her positioning: a far-right candidate trying to occupy the fiscally responsible centre ground that Macron has vacated.
The bond market’s relative comfort with Le Pen compared to Mélenchon reflects a specific calculation. Hard-left candidate Jean-Luc Mélenchon has suggested writing off the 20 percent of France’s debt currently held by the central bank, a proposal that would be technically complex, potentially illegal under EU treaty obligations, and deeply alarming to creditors. A Mélenchon presidency arriving in the context of the current fiscal situation would test the market’s reaction in ways that no French politician has faced since at least the early 1980s.
With far-right and far-left candidates in the lead to become France’s next president in the spring, markets are losing confidence that either side will take the difficult steps necessary to restore fiscal order. A significant and sustained fiscal effort is required beyond the presidential elections to stabilise the debt burden, which is on track to hit 122 percent of GDP next year. But neither of the leading candidates presents a programme that clearly delivers that effort.
What This Means for the Eurozone
France is not a peripheral economy. It is the eurozone’s second-largest economy and, with Germany, one of the two pillars on which the European monetary union rests. The crisis currently unfolding in Paris carries implications that extend to every country that shares the euro.
The most immediate concern is contagion. When bond markets lose confidence in one major eurozone sovereign, they tend to reassess others. Italy’s bond yield has already risen alongside France’s, though Italy is currently the more credible fiscal story given the consolidation steps taken under Meloni. Spain has benefited from stronger economic performance. But a sustained deterioration in French bond yields, particularly if it crosses into territory that triggers concerns about debt sustainability, could restart the kind of market dynamics that made the 2011-2012 eurozone debt crisis so acute.
The European Central Bank faces a particular dilemma. It has been raising rates in response to inflation driven by the Iran war energy shock. Those rate rises directly increase France’s borrowing costs on new debt issuance. But a pivot to rate cuts, or the activation of the ECB’s Transmission Protection Instrument to purchase French government bonds and cap yield spreads, would require a political commitment from France to credible fiscal consolidation that the current French government is unable to make given its parliamentary situation and the social pressure in the streets.
The European Commission’s excessive deficit procedure against France, which requires a credible consolidation plan, is also constrained by political reality. The Commission can recommend, pressure, and ultimately sanction. But it cannot govern France. It cannot pass a French budget. And it cannot prevent a French president from calling elections whose result produces an ungovernable parliament.
For European partners watching from Berlin, Amsterdam, Stockholm, and Vienna, the France situation is a reminder that the eurozone’s architecture contains a structural vulnerability: a shared currency whose credibility depends on fiscal discipline that ultimately each member state must enforce on itself, with limited tools available to the centre when that self-enforcement fails.
Three Scenarios for What Comes Next
The budget passing and markets stabilising is the first scenario. The National Assembly eventually approves the 2027 budget, possibly with modifications that reduce its ambition further but provide the political legitimacy that an executive decree would lack. Protests continue on October 24 as planned but at lower intensity than October 17. Moody’s on October 23 holds its rating steady. Bond yields ease back from the 4.9 percent peak as immediate uncertainty resolves. France enters the presidential campaign with its fiscal position still problematic but not in active crisis. This is the scenario that the Lecornu government and European partners are working to achieve. Its probability depends on whether the parliamentary arithmetic can be made to add up to at least a minimally credible budget.
The downgrade and escalation scenario is the second path. Moody’s on October 23 cuts France’s rating by one notch, triggering automatic selling by institutional investors constrained by rating floors, pushing yields above 5 percent. The October 24 protests prove larger than the October 17 protests as autumn school holidays end and students and unions return to the streets. The parliamentary budget debate stalls entirely. The spread between French and German yields widens toward the 200 basis point level that would trigger ECB intervention discussions. Le Pen’s poll lead widens further as her fiscally responsible rebranding gains traction in a climate of establishment failure. France enters the spring election campaign in the middle of an active market crisis.
The managed uncertainty scenario is the third and most likely path. Moody’s holds its rating steady but with an explicitly negative outlook, giving France a brief respite while maintaining maximum pressure for credible action. The budget passes in weakened form, possibly by decree, reducing the deficit to 5.2 rather than 5 percent of GDP. Bond yields stabilise in the 4.7 to 5 percent range through the winter, painful but not spiralling. Protests continue at a lower intensity through October and November. The presidential campaign begins in January 2027 with France’s fiscal credibility as the defining issue. Markets wait for the election result before reassessing.
The Bottom Line
France is not Greece in 2010. It is a far larger, more complex, and more systemically important economy, which means both that a French debt crisis would be more damaging than the Greek episode and that European institutions have stronger incentives to prevent it from reaching that stage. The ECB’s toolkit, the ESM’s lending capacity, and the political will of European partners to avoid a eurozone fracture are all real constraints on how bad the situation can become.
But those tools require activation, and activation requires conditions that France has not yet met. The ECB’s Transmission Protection Instrument requires the beneficiary to comply with the EU fiscal framework. The ESM’s conditionality requires a government programme capable of credible implementation. Neither condition is currently satisfied in France.
Ultimately, the numbers that describe France’s situation, a 119 percent debt-to-GDP ratio, bond yields at 24-year highs, a deficit double the eurozone average, an interest bill of €65.7 billion annually, and five prime ministers in two years, are not the cause of the crisis. They are the accumulation of years of political decisions that prioritised the avoidance of difficult choices over the management of long-term fiscal reality.
The student who blocked her school in Créteil in September was not thinking about bond spreads. The Yellow Vest who joined Saturday’s march because fuel costs €2.20 a litre was not calculating debt-to-GDP ratios. But the market that pushed France’s 10-year yield to 4.92 percent on Monday was calculating all of it, and what it was calculating was whether France can find the political will to close the gap between what it spends and what it earns before that gap becomes a chasm that neither elections nor European institutions can bridge.
That is the question that will define France, and possibly the eurozone, across the next six months.
Sources: Reuters, October 19, 2026; Fortune, October 17 and October 24, 2026; CNBC, October 13, 2026; France 24, October 9, 2026; Euronews, October 24, 2026; CNN, October 19, 2026; Al Jazeera, October 20, 2026; Eurasia Business News, October 4, 2026; IndexBox/Moody’s, October 24, 2026; ING/BFM Bourse, October 20, 2026; Eurostat, October 21, 2026; TrendCompass, October 20, 2026.
Related Articles: