China’s demographic shift toward an ageing population presents a potential opportunity for Europe seeking demographic balance. This misconception poses significant risks: the demographic crisis in Beijing is exacerbating competition for global markets.
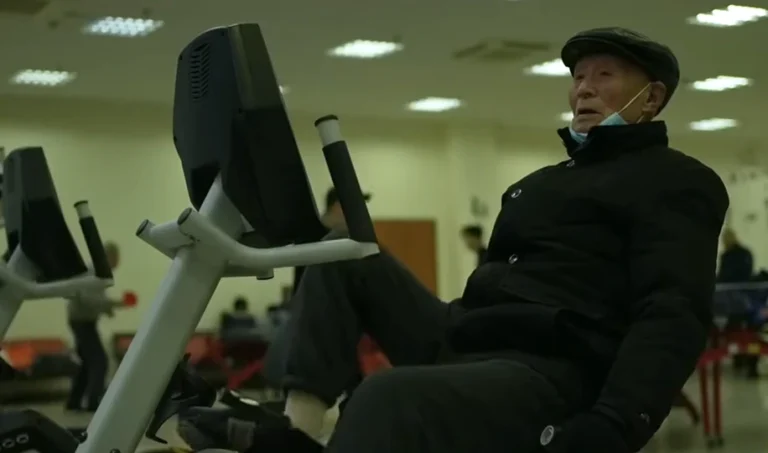
China’s demographic “crisis” is on everyone’s lips. Reports highlight the immense challenges Beijing faces due to its rapidly ageing population: rising social spending, declining labour force participation, and sluggish consumer spending. Proponents of the “Peak China” theory argue that, contrary to initial predictions, China may never overtake the US as the world’s largest economy. At the same time, it is suggested that Europe is better prepared for demographic change. There appears to be a significant level of schadenfreude present.
However, those anticipating a reduction in competition from China are likely to be misled. The opposite is likely to be true: The ageing population increases the pressure on the Chinese leadership to structurally reorganise its economy and further advance its aggressive industrial policy – with direct consequences for European industry. China’s demographic weakness could thus become an economic challenge for Europe.
For decades, Beijing’s economic model has relied on state-directed investment in the construction industry and manufacturing for export—two key drivers of the Chinese economy. Although China has gradually expanded its social welfare system, it still provides only a limited social safety net, primarily for the urban middle class. Because many households still need to save for education, housing, healthcare, and elder care, domestic private consumption in China accounts for only 3.8 percent of GDP—compared to a global average of 6.0 percent .
Although Beijing has long attempted to reform its social welfare system and shift towards consumption-driven economic growth, this endeavour has so far been hampered by the legacy of its investment-driven economic model. The two “engines” of the Chinese economy generate enormous overcapacities. However, weaker global demand following the global financial crisis and trade conflicts since 2015 have hampered exports. Most recently, a real estate crisis and high youth unemployment have exacerbated the economic situation.
Demographic change is increasingly constraining Beijing’s options for action. China is ageing significantly faster than Europe – and it is doing so at a comparatively low income level. While in Germany, one of Europe’s oldest countries, the birth rate is 1.4 children per woman; it has fallen to 1.0 in China. Even the shift to the “two-child” and finally the “three-child” policy could not halt this decline. Moreover, China is not relying on immigration from abroad. The consequences for the labour market are considerable: Whereas previously there were five working-age people for every retiree, forecasts predict that in 25 years there will be only 1.6.
Population ageing is already putting enormous pressure on China’s pension and healthcare systems. The resources of the basic workers’ pension system may be depleted by 2035. While the government raised the retirement age in 2024 for the first time in decades – from 50 to 55-58 years for women and from 60 to 63 years for men – it will take a long time for these reforms to bear fruit. And even then, they can only alleviate, not eliminate, the financial burden. Additionally, there is a significant disease burden: approximately 91 percent of deaths in China are attributed to chronic diseases (compared to a global rate of 74 percent), leading to a swift rise in both private and public healthcare expenditures. Beijing is therefore already having to redirect more funds into the social security system – resources that are actually needed to stimulate the economy.
Moreover, the ageing population is further dampening already weak domestic consumption. Researchers indicate that demographic change is responsible for approximately 50 percent of the savings in Chinese households. China is at risk of entering a phase of prolonged economic stagnation, marked by low consumption levels and elevated savings rates that hinder investment opportunities. This situation bears resemblance to the one observed in Japan. Beijing faces a pressing deadline. The leadership needs to ensure that industrial production operates at maximum capacity to preemptively address the potential challenges posed by demographic shifts. The demographic crisis is not compelling Beijing to withdraw; instead, it is propelling its industrial policy forward.
To overcome prolonged stagnation, Beijing is depending on substantial technological advancements. Industrial robots are designed to sustain production levels in light of a declining working-age population. Robotics and digital technologies are designed to enhance the efficiency of elderly care and medical services while reducing reliance on personnel. Since 2016, Beijing has been actively promoting the Silver Economy, which focuses on the market for products and services tailored for older individuals. Forecasts indicate that this market is projected to expand to an estimated 30 trillion renminbi (approximately 3.9 trillion euros) by 2035, thereby creating new consumption opportunities.
These measures, nonetheless, can only offer a constrained level of relief. While the silver economy is expanding, there exists a concern that its advantages may predominantly serve the upper middle and upper classes. This ageing population may intensify social inequality and societal tensions. Simultaneously, the automation of production fails to address the issue of overcapacity. Chinese companies must continue to sell their goods on the global market, even if it requires offering them at reduced prices.
This is exactly where China’s demographic crisis poses a challenge for Europe. Beijing’s efforts to stabilise its economy by enhancing export orientation may intensify the phenomenon referred to as “China Shock 2.0. Trade experts have noted a significant rise in affordable export products from China, which are no longer confined to low-tech sectors. This trend is now expanding into high-tech areas, including the automotive industry, renewable energies, and industrial robotics.
For European industry, this presents a dual challenge: the low prices of Chinese products diminish the profits of European companies and escalate competitive pressure, while simultaneously obstructing investment in digital and green technologies that could enhance European competitiveness over the long term. Beijing is expected to implement its industrial policy with diligence to prevent economic stagnation and uphold its political legitimacy. China’s ageing population, its industrial policy, and the increasing competitive pressure on Europe are interconnected factors.
Europe needs to adopt a flexible strategy in response to this development. Tariffs and import restrictions by themselves do not adequately address the complexities of the situation, as the supply chains of Europe and China are intricately linked. Universal import restrictions elevate the expenses associated with intermediate goods for the European industrial sector. Furthermore, they do not impede Chinese exports to significant third markets in Southeast Asia or Africa, where European companies are progressively facing increased competition. Moreover, the US tariffs imposed on Chinese products yielded counterproductive outcomes for the United States: Beijing responded with retaliatory actions and restricted access to rare earth elements.
De-risking is a crucial measure in this context, yet it is not a comprehensive solution. Strategies such as “China+1” are essential for mitigating dependencies over the long term. Nevertheless, the process is lengthy and comes with constraints: China’s domestic market is significantly expansive, and its pivotal position in global value chains makes it impractical for Europe to fully disengage. Furthermore, the “China+1” strategy frequently introduces additional intermediaries into supply chains, failing to address the fundamental competitive challenges.
Europe’s trade and industrial policy needs to adopt a more adaptable, sector-focused, and, most importantly, more anticipatory approach. Rather than simply responding to China’s export strategy, Europe ought to strategically leverage Beijing’s challenges. Three approaches can be identified:
Initially, given that Beijing requires the European market to address its overcapacity, it is essential for Europe to establish a stronger connection between market access and specific conditions. This could include stipulations regarding the transfer of technology and intellectual property from China to Europe, as well as investments in local research and development. This is especially relevant in sectors where China has established a technological advantage, including battery technology and green technologies. This would reduce the investment burden on European companies and enhance their technological advancement.
Secondly, the growing ageing population in China is driving an increased demand for advanced medical and nursing technologies, along with pharmaceutical products. This indicates potential avenues for collaboration. European companies have the potential to leverage this opportunity and gain advantages from Beijing’s initiatives aimed at enhancing consumption within the healthcare sector.
Thirdly, Europe should expedite its investments in critical technologies such as robotics, AI, and automation, while also implementing the recommendations of the Draghi report with greater urgency to mitigate dependencies in the high-tech sector.
China’s demographic ageing should not be interpreted as a signal to relax or assume that challenges have been resolved. On the contrary, it exacerbates an already intense economic rivalry. Not despite, but precisely because of its ageing population, Beijing is advancing a heavily state-subsidised export strategy that is significantly intensifying the pressure on Europe’s key industries. Europe must recognise China’s demographic change as a geoeconomic challenge that requires a competitive and strategically sound response.
The author, Dr Christina Maags, holds the position of Senior Lecturer at the University of Sheffield. She formerly instructed at SOAS University of London and served as a visiting professor of political science specialising in area studies of China/East Asia at Goethe University Frankfurt am Main.
The article first appeared on IPG in German.
Fang Taozi: China’s AI Actress Has 250 Million Views and Real Advertising Deals in 2026
The Qaidam Basin: China’s Hidden Energy Arsenal and the Geopolitical Battle for Critical Minerals
Shiziguan Floating Bridge: China’s Most Mesmerising and Controversial Water Highway in 2026
From Tariffs to Tech Controls: Inside the Renewed U.S.–China Trade Conflict